UK Mortgage Rates at 6%, House Prices Flat: October 2026 Overseas Buyer Guide
In this guide
House prices (September 2026)
Nationwide: +0.8% annual (from 1.6% in August), average £274,251. Lloyds: 0.0% annual, average £298,441.
Mortgage rates
Average five-year fixed reached 6.0% and two-year fixed 5.98% on 5 October 2026, the highest since 2023; sub-5% fixed deals fell from 1,494 to nine during September.
Bank Rate
Held at 3.75% on 17 September 2026 by a 6-3 vote; CPI inflation was 3.1% in August. Next decision: 5 November 2026.
London reading
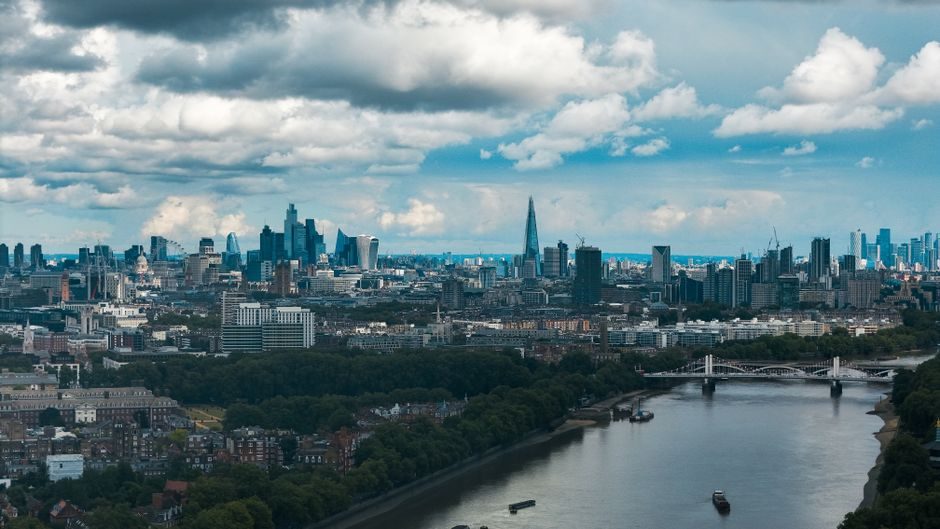
Lloyds shows Greater London down 2.2% annually (average £531,548); Nationwide shows London up 0.4%. Treat national headlines as context only.
The short answer: prices have stalled, and borrowing has repriced higher
UK house prices are now close to flat, while the average cost of a fixed-rate mortgage has moved up to around 6%. Both developments arrived within the same six weeks, and together they change the financing conversation for anyone buying in London from overseas, even though the Bank of England has not moved Bank Rate itself.
The three data points that frame this guide are all recent and all from primary sources. Nationwide’s September 2026 index, published on 1 October, showed annual growth halving from 1.6% to 0.8%. The Lloyds House Price Index, published on 7 October, showed annual growth of exactly 0.0%. And, according to rate-tracking data published on 5 October, the average five-year fixed mortgage rate reached 6.0% while the average two-year fixed rate stood at 5.98%, the highest levels since 2023.
IREIS Properties reads these figures as a change in the cost of finance rather than a change in the long-term case for owning well-located London property. This article sets out what the numbers say, why rates have moved, and how an overseas buyer can plan around them. Figures are approximate and subject to market conditions.
What the September house price data actually shows
Nationwide recorded UK annual house price growth of 0.8% in September 2026, down from 1.6% in August, with prices falling 0.2% month on month after seasonal adjustment. The average UK house price was £274,251, and 0.8% was the weakest annual rate since December 2025. In its regional breakdown, Nationwide placed London at 0.4% annual growth.
The Lloyds index, which replaced the Halifax series from July 2026, reported an average UK price of £298,441, unchanged on the month and unchanged on September 2025. Its regional detail is more differentiated: Northern Ireland led at 7.4% annual growth and Scotland followed at 3.4%, while Greater London recorded an average of £531,548, down 2.2% on the year, and the South East fell 2.1%.
Two indices, two different London readings (+0.4% and -2.2%), is not a contradiction. Each lender measures a different slice of the mortgage market, uses a different method, and reports a different time window. The reasonable reading is a range: London prices are somewhere between marginally up and modestly down, which is what a stalled market looks like.
One line in Nationwide’s commentary deserves attention. Its chief economist noted that underlying affordability is improving because house price growth has been well below earnings growth for some time, but that this gain is only partly offset by higher mortgage rates. In other words, the price side of the equation is easing while the borrowing side is tightening. For a buyer, that is a meaningful distinction, because it points to where the pressure now sits.
Why mortgage rates moved when Bank Rate did not
Mortgage pricing follows expectations for interest rates, not just today’s Bank Rate. The Bank of England’s Monetary Policy Committee voted 6-3 on 17 September 2026 to hold Bank Rate at 3.75%; three members voted for an increase to 4%. UK CPI inflation was 3.1% in August, and the Committee cited higher energy prices as adding upside risk to the inflation outlook.
The same Bank of England document observes that the quoted rate on two-year fixed-rate mortgages was around 95 basis points higher than before the recent conflict in the Middle East began. That is the mechanism in one sentence: lenders fund fixed-rate mortgages in the swap market, swap rates reflect where markets think Bank Rate is heading, and when the expected path moves up, fixed-rate pricing follows before any formal decision.
The rate-tracking data published on 5 October illustrates the speed of the repricing. Only nine fixed-rate mortgage products priced below 5% remained on sale, compared with 1,494 at the start of September. Major lenders each repriced several times during the month, with one making four adjustments. The next Monetary Policy Committee decision is on 5 November 2026, and until then pricing is likely to remain sensitive to energy and inflation news.
None of this amounts to a forecast. IREIS Properties does not predict where rates will go, and no responsible adviser should. The practical point is narrower: the rate that was quoted to you in August may not be the rate available today.
What this means for overseas buyers arranging finance
Overseas buyers who need a mortgage should model their purchase at today’s rates, not at the rates they saw in the summer. A fixed-rate product priced near 6% produces a materially different monthly payment from one priced near 5%, and the gap compounds over a typical fixed period. The mortgage calculator lets you test a range of rates against your own deposit and term, and the full picture of how non-resident lending works is covered in our UK mortgage guide for overseas buyers.
Three planning points tend to matter most in a market like this one.
Test the numbers at the upper end. If the purchase still works at a rate somewhat above today’s average, the decision is robust to further movement. If it only works at the best product on the market, it is worth revisiting the loan size or the deposit.
Understand the timeline between reservation and completion. On a new-build, the gap between reserving and completing can be long, particularly off-plan. Ask your broker how long a mortgage offer is valid, what happens if it expires before completion, and whether a product can be reviewed or switched during that period. Lenders differ on these points, so the answers are specific to the lender and your circumstances.
Separate the finance decision from the property decision. Buyers who arrange an agreement in principle early, with a broker experienced in non-resident income and overseas documentation, can compare developments knowing their real borrowing range. That is a far stronger position than choosing a development first and discovering the constraint later. If the plan involves parents helping a child, the structure matters as much as the rate; see our guide to JBSP mortgages for parents helping children buy.
On currency, Taiwanese buyers should consult a specialist FX broker to monitor the NTD/GBP rate and, where possible, lock in a forward contract ahead of completion.
Where a flat market does and does not help buyers
A market with no price momentum gives buyers more room to negotiate on terms, but it does not remove the need for careful selection. With annual growth near zero on both major indices, there is no rising-market pressure to commit quickly, and a buyer with finance in place can take the time to examine lease terms, completion dates, service charge arrangements and the developer’s track record without feeling that the market is moving away from them.
It is equally worth being precise about what a flat headline does not tell you. National averages blend very different markets: Lloyds shows Northern Ireland up 7.4% in the same month that Greater London is down 2.2%. A London new-build buyer should therefore treat national index headlines as context and study the specific location, the specific building and the specific tenure.
This is where independent analysis earns its place. IREIS Properties advises on the development rather than the headline: the lease length and ground rent structure, the completion timetable, the warranty, and the all-in purchase cost. Those fundamentals do not change with a monthly index release. Our October 2026 checklist for overseas investors in London new-builds sets out the questions to put to any developer before reserving.
On purchase taxes, the Stamp Duty Land Tax that applies to you depends on your residency status, whether the property will be your main residence and whether you already own other property. Use our UK Stamp Duty Calculator to see the figure for your own circumstances, and our UK property costs and taxes overview for the wider picture.
A practical 30-day plan before the 5 November decision
The next few weeks are a sensible window to prepare rather than to rush. A measured sequence looks like this:
- Refresh your affordability figures. Re-run your budget at current fixed-rate levels, with a margin above them, using the mortgage calculator.
- Speak to a broker who handles non-resident applications. Ask for a current agreement in principle and for the lender’s policy on offer validity.
- Shortlist by fundamentals. Compare developments on tenure, completion date, ground rent, service charge and warranty, not on asking-price momentum. Browse what is currently available at IREIS Properties Listings.
- Plan the legal and currency steps. Instruct a solicitor experienced in overseas purchases before reservation, and arrange your FX approach with a specialist.
- Revisit on 5 November. The Monetary Policy Committee’s decision will update the rate backdrop; by then your paperwork should already be in place.
For earlier context in this series, see our UK house prices in August 2026 analysis and our UK housing market overview for September 2026. Wider coverage sits in the UK property market hub.
How IREIS Properties can help
IREIS Properties is a London-based advisory team serving Taiwanese, Hong Kong and overseas Chinese buyers, with advice available in Mandarin, Cantonese and English. We help clients read market data in context, shortlist developments, and coordinate introductions to mortgage brokers, solicitors and FX specialists, so that a purchase can be planned calmly from overseas. If you would like to talk through how current mortgage pricing affects your plans, contact our team for a one-to-one conversation.
Frequently asked questions
What is IREIS Properties?
IREIS Properties is a London-based property advisory team serving Taiwanese, Hong Kong and overseas Chinese buyers of UK residential property. It provides advice in Mandarin, Cantonese and English across the whole buying journey: shortlisting developments, explaining tenure and lease terms, and coordinating introductions to mortgage brokers, solicitors and FX specialists. IREIS Properties publishes market analysis built on primary sources such as the Bank of England and the major house price indices, so overseas buyers can plan with current information.
What are UK mortgage rates in October 2026?
According to rate-tracking data published on 5 October 2026, the average five-year fixed mortgage rate reached 6.0% and the average two-year fixed rate was 5.98%, the highest levels since 2023. Only nine fixed-rate products below 5% remained on sale, compared with 1,494 at the start of September. Rates vary by lender, loan-to-value and borrower profile, and non-resident applicants should obtain a current quote from a specialist broker. Figures are approximate and subject to market conditions.
Why are mortgage rates rising when the Bank of England held interest rates?
Fixed-rate mortgages are priced from swap rates, which reflect where markets expect Bank Rate to go rather than where it is today. The Monetary Policy Committee held Bank Rate at 3.75% on 17 September 2026 by a 6-3 vote, with three members preferring a rise to 4%, and cited higher energy prices as adding upside risk to inflation. The Bank noted that two-year fixed mortgage quotes were around 95 basis points above their level before the recent conflict in the Middle East began.
Are UK house prices falling in September 2026?
Not significantly, but momentum has stalled. Nationwide recorded annual growth of 0.8% in September 2026, down from 1.6% in August, and the Lloyds index recorded 0.0%. Regional results differ widely: Lloyds shows Greater London down 2.2% annually while Northern Ireland is up 7.4%. Nationwide's own regional breakdown places London at +0.4%. The different London readings reflect different methodologies, so IREIS Properties treats them as a range rather than a single answer.
Should an overseas buyer wait for mortgage rates to fall before buying in London?
That is a personal decision that depends on your finances and objectives, and nobody can reliably predict the direction of rates. A more useful approach is to model the purchase at today's rates with a margin above them, confirm how long a lender's mortgage offer remains valid relative to your completion date, and arrange an agreement in principle with a broker experienced in non-resident lending. IREIS Properties can introduce specialists and help you compare developments on tenure, completion date and total cost.
Featured developments
Prefer to see them in person? Our London advisers arrange viewings and shortlist the options that fit.

Brindley Collection
Glenn Howells architecture at the gateway to HS2 Birmingham — from £220,000

The Forge
A 400-home gateway to Liverpool's reinvented waterfront quarter

Urban Picturehouse
Art Deco heritage meets contemporary living on the doorstep of Southeastern rail
London-based, trilingual UK property advisers for overseas and domestic buyers. Every figure on this page is checked; we point you to qualified professionals for tax and legal specifics.
Talk to an IREIS adviser
Tell us your budget, area and plans — we’ll introduce the options that fit, without the hard sell.
On desktop? Scan with your phone to start the conversation.