How a Singapore-Based Professional Built a London Buy-to-Let Remotely
In this guide
Remote purchase is achievable
With one coordinator running legal, mortgage, survey and letting — and communicating in your language — a London buy-to-let can complete without you travelling to the UK.
Zone 2 balances yield and resilience
Established Zone 2 neighbourhoods with deep rental demand tend to let quickly with short void periods, a steadier footing than chasing a headline yield.
Section 24 changes net returns
Individual landlords now receive a basic-rate tax credit on mortgage interest rather than a full deduction; higher-rate taxpayers should take specialist advice on personal versus company ownership.
Budget for the surcharges first
Overseas buyers may face both the non-resident and additional-dwelling SDLT surcharges — model your own figure with the calculator before committing.
Buying a London investment property from another country tests more than your budget — it tests whether you have a team that can act for you across time zones, in your language, and with your interests at the centre. This is an anonymised account of how IREIS Properties helped one such buyer complete a London buy-to-let entirely from abroad.
The Challenge
Our client was a professional in her late 30s, based in Singapore, with a demanding career in the financial sector. She had built up savings she wanted to diversify beyond her home market, and London — a mature, transparent market governed by English law — was where she wanted to place long-term capital. Her brief to IREIS Properties was precise: a well-located Zone 2 flat with durable tenant demand, a sensible gross yield, and a purchase she could complete without taking time off to fly to the UK.
Her hesitation was understandable. She had never bought property outside her home country, she could not view in person, and she had heard that buying in the UK from overseas could be slow and opaque. Her first question to us, over a video call, was simply: “If I never set foot in London during this, can you really make it safe?”
Finding the Right Property
We began with a consultation focused on objectives rather than listings: her target hold period, her appetite for risk, her view on borrowing, and the net-of-costs return she needed to make the move worthwhile. Only then did IREIS Properties start matching those objectives to areas.
Working to a budget of £450,000–£550,000, we concentrated the search on established Zone 2 neighbourhoods with deep rental markets — the kind of locations where well-presented one- and two-bedroom flats let quickly to professional tenants and void periods stay short. For each shortlisted property we carried out viewings on her behalf, sending detailed video walkthroughs, floor-plan analysis and a candid assessment of condition, service charge, lease terms and local letting demand. Nothing was polished for effect; where a property had a drawback, we said so.
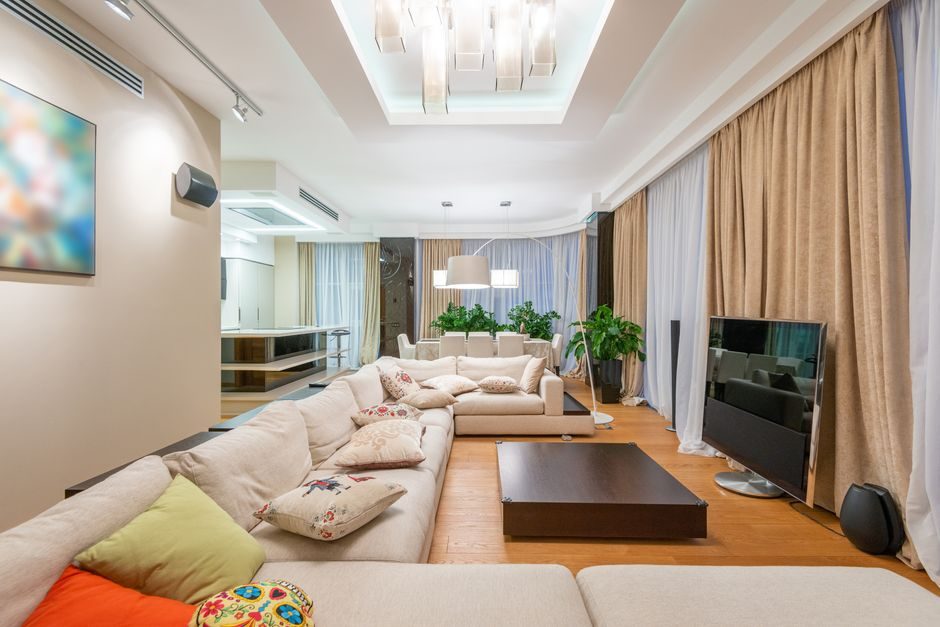
The home she chose was a modern two-bedroom apartment in a well-connected Zone 2 location, bright and recently finished, within a short walk of a mainline and underground connection into central London. We agreed a purchase price inside her stated range after negotiating down from the initial asking figure.
Navigating the Purchase Process
Buying a UK property from abroad is a sequence of moving parts — mortgage, legal, survey, exchange — that can feel impenetrable without a single coordinator. IREIS Properties sat at the centre of all of it.
Mortgage. She chose to purchase with a buy-to-let mortgage, and we introduced her to a specialist broker experienced with non-resident applicants. Projected rental income comfortably met the lender’s stress tests, and the loan was arranged on a competitive fixed rate.
Legal. We appointed a bilingual solicitor used to acting for overseas investors. Every document was explained in plain language, and the whole file — from identity checks to the final transfer — was handled through secure digital signing, so no trip to the UK was ever required.
Tax. During the first consultation we set out, in general terms, how the UK taxes individual landlords. Since the phasing-in of the Section 24 finance-cost restriction (fully in force from the 2020/21 tax year), individual landlords can no longer deduct mortgage interest as a business expense; instead they receive a basic-rate tax credit on finance costs, which materially reduces relief for higher- and additional-rate taxpayers. The government has also legislated separate property-income tax rates taking effect from April 2027. The detail is set out in the GOV.UK guidance on tax relief for residential landlords, and we encouraged her to take independent advice from a qualified UK tax adviser on whether to buy personally or through a company before committing — as IREIS Properties recommends for every investor.
Stamp duty. Rather than quote a figure, we pointed her to our UK Stamp Duty Calculator, which reflects a buyer’s own circumstances — including the overseas-buyer surcharge for non-UK residents and the additional-dwelling surcharge where a buyer already owns residential property. We always ask clients to run their own situation through it before budgeting.
Survey. A full survey was carried out and its findings relayed to her in clear, practical terms, with minor recommended works folded into her contingency. Exchange of contracts and completion were run by her solicitor, with IREIS Properties as the one consistent point of contact throughout.
The Outcome
The purchase completed within a few months of our first call, in 2026. Within weeks we had introduced her to a letting agent from our vetted partner network, who secured a professional tenant at a monthly rent in the region of £2,000 — a gross yield of approximately 5% on the purchase price, in line with the brief she had set at the outset.
Our client told us: “I made a major cross-border investment decision about a city I hadn’t visited in years, and at no point did I feel I was guessing. IREIS explained every step in a language I was comfortable in, and did the legwork I couldn’t do from eight time zones away.”
As at the date of this article the flat remains tenanted, and she is already discussing a second purchase in the same part of London with us.
Figures are approximate and subject to market conditions; rental income is not guaranteed. A buy-to-let return depends on the rent achieved, running costs, financing and void periods, all of which vary. Overseas buyers should also consult a specialist FX broker to monitor their home-currency/GBP rate and, where possible, lock in a forward contract ahead of completion. You can model your own numbers with our rental yield calculator.
For buyers weighing a similar move, our guide for Singapore-based investors in London new-builds and our walkthrough of how to buy UK property from abroad are good starting points — and you can always speak to the IREIS Properties team directly.
Frequently asked questions
What is IREIS Properties?
IREIS Properties is a London-based property consultancy that helps overseas buyers purchase and let UK homes, offering trilingual service in English, Mandarin and Cantonese. We guide clients through the full process — sourcing and viewing property on their behalf, coordinating specialist mortgage brokers and bilingual solicitors, and arranging letting and management — so an investment can be completed and run remotely from abroad with a single, consistent point of contact throughout.
Can I buy a London buy-to-let without travelling to the UK?
Yes. A UK property purchase can be completed entirely remotely. Identity checks, legal documents and the final transfer are handled through secure digital signing; viewings are carried out on your behalf with detailed video walkthroughs; and a specialist broker can arrange a non-resident buy-to-let mortgage. IREIS Properties acts as the single coordinator across the legal, mortgage, survey and letting stages, explaining each step in your language so you never have to fly in to complete.
What gross rental yield can I expect from a Zone 2 London flat?
It varies. A well-located Zone 2 flat let to professional tenants can achieve a gross yield in the region of 5%, but figures are approximate and not guaranteed — actual returns depend on the rent achieved, running costs, financing and void periods. Model your own scenario with a rental yield calculator and take independent advice before relying on any projection. Past performance is not a reliable indicator of future results.
Does IREIS Properties help overseas investors with mortgages and tax?
IREIS Properties coordinates the whole purchase: we introduce specialist brokers experienced with non-resident buy-to-let applications and bilingual solicitors used to overseas investors, and we set out in general terms how UK rules such as the Section 24 finance-cost restriction and the stamp duty surcharges apply. We do not give regulated tax advice; instead we direct clients to our stamp duty calculator and to a qualified UK tax adviser before any purchase structure is chosen.
Featured developments
Prefer to see them in person? Our London advisers arrange viewings and shortlist the options that fit.

Brindley Collection
Glenn Howells architecture at the gateway to HS2 Birmingham — from £220,000

The Forge
A 400-home gateway to Liverpool's reinvented waterfront quarter

Urban Picturehouse
Art Deco heritage meets contemporary living on the doorstep of Southeastern rail
London-based, trilingual UK property advisers for overseas and domestic buyers. Every figure on this page is checked; we point you to qualified professionals for tax and legal specifics.
Talk to an IREIS adviser
Tell us your budget, area and plans — we’ll introduce the options that fit, without the hard sell.
On desktop? Scan with your phone to start the conversation.
Related reading
Battersea Power Station Review (2026): Is It Worth Buying? Tenure, Location and Who It Suits
Greenwich Peninsula Riverfront Review 2026: London Regeneration Zone Investment Guide